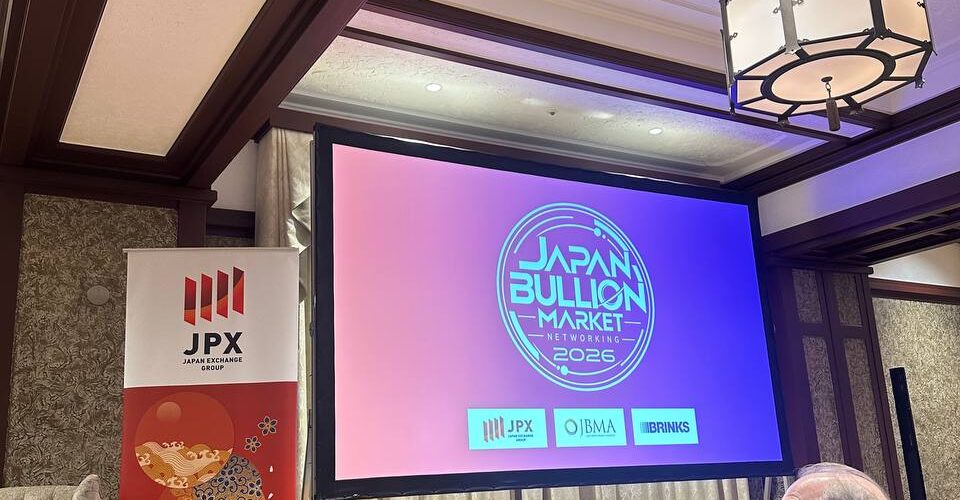
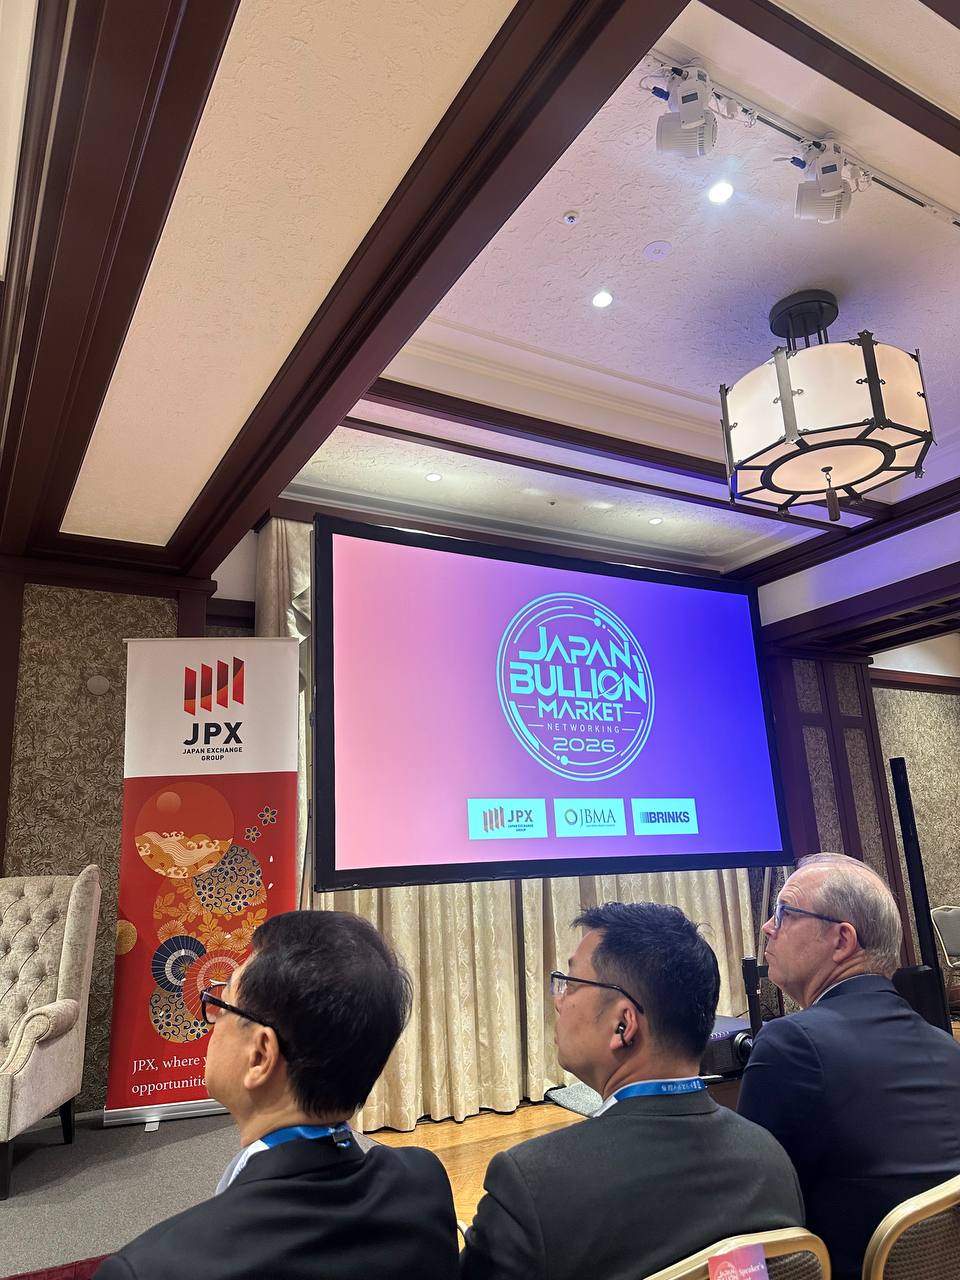
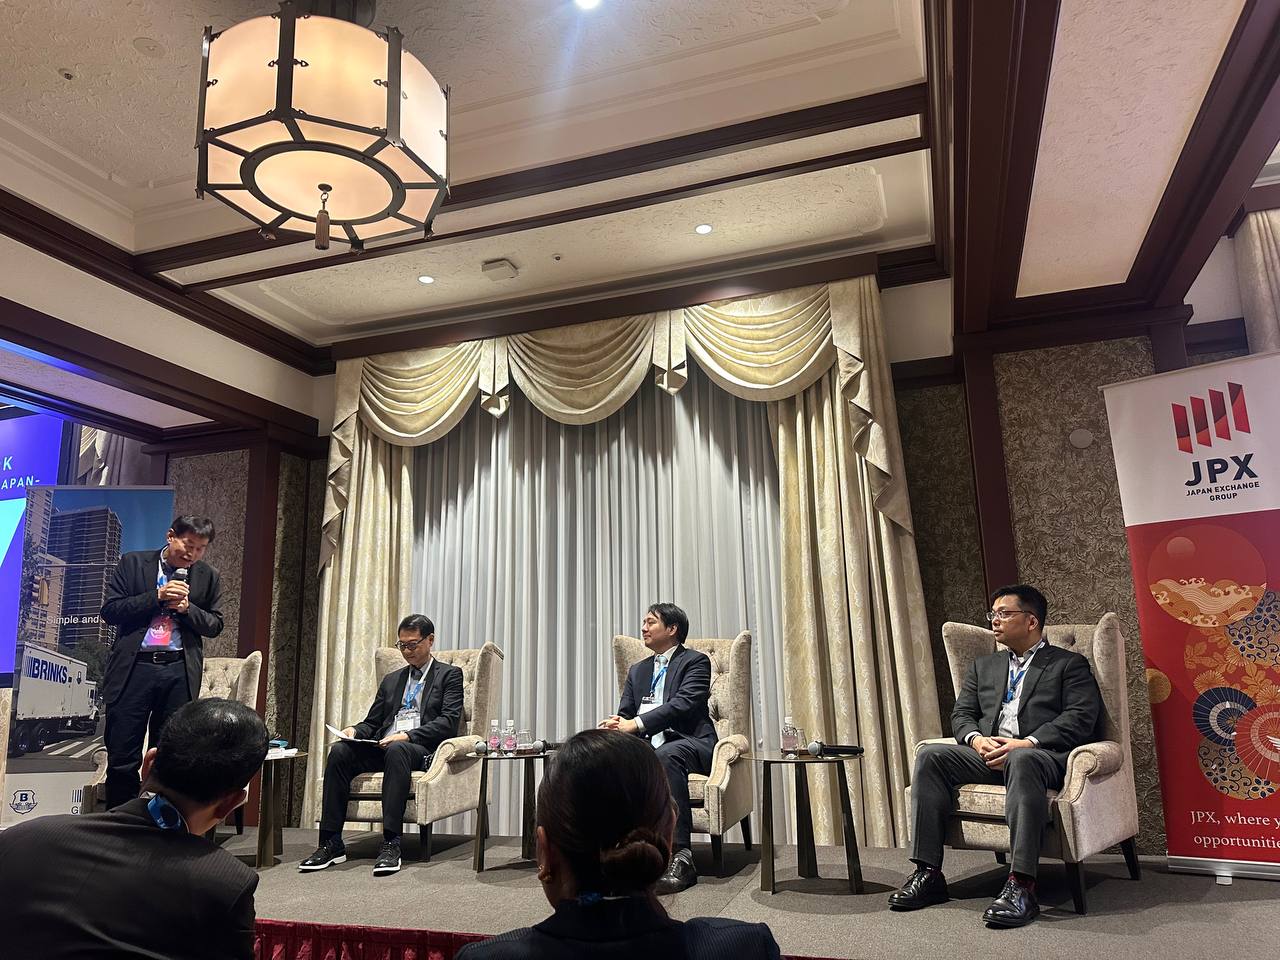
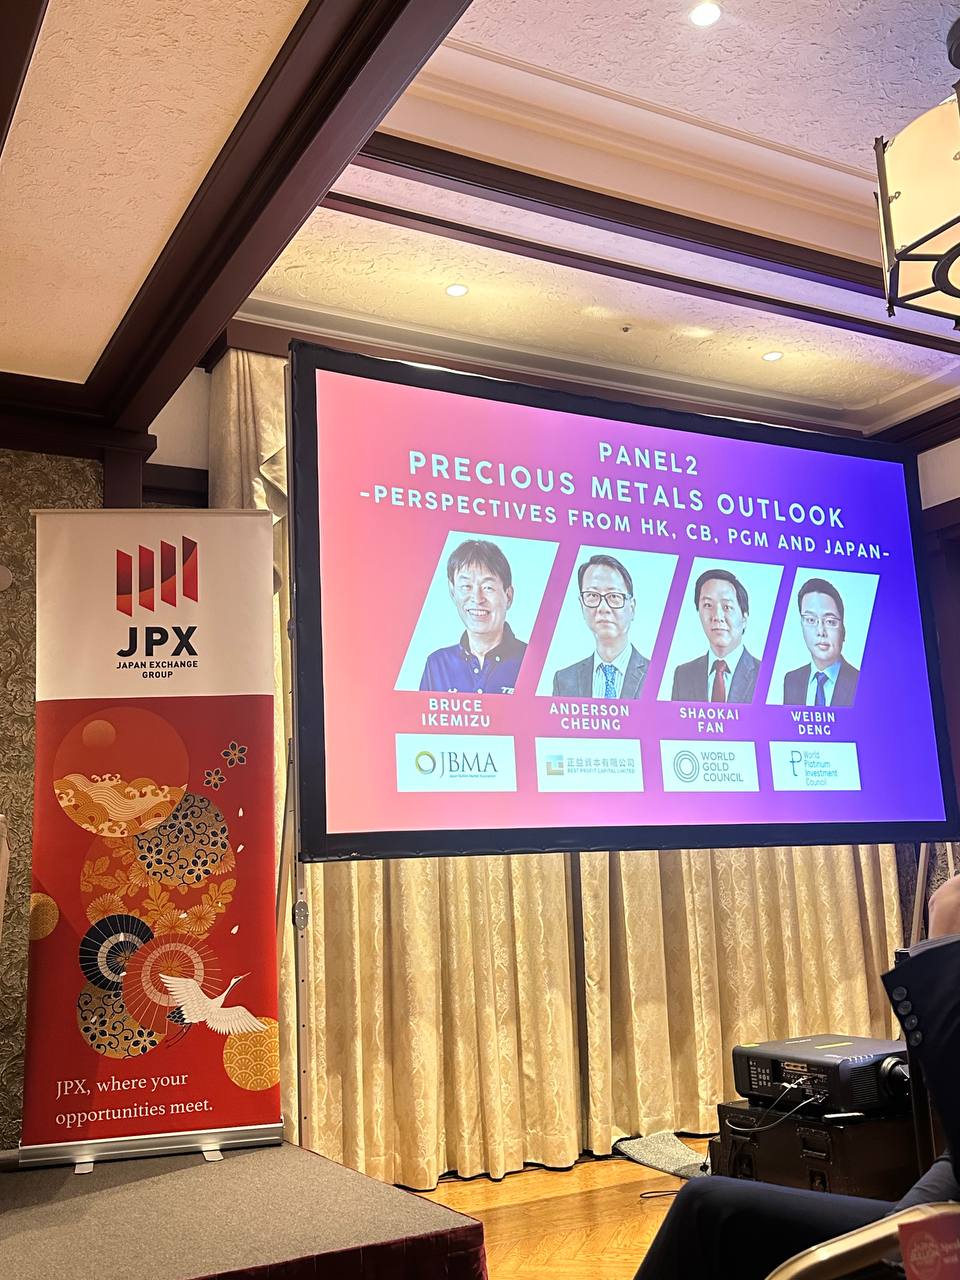
Tokyo, 4 November 2026 — UniPrecious Metal attended Japan Bullion Market Networking 2026, organised by the Japan Bullion Market Association (JBMA). The event brought together professionals from across the precious metals industry for discussion and exchange on developments in Asian and international markets.
Industry dialogue with a regional perspective
The programme included networking and a panel examining the outlook for precious metals. Perspectives relating to Hong Kong, Japan and platinum group metals highlighted the breadth of issues relevant to market participants. For UniPrecious Metal, these conversations offered a valuable opportunity to follow industry priorities and consider how different markets respond to changing conditions.
Headquartered in Hong Kong and focused on precious metals trading, UniPrecious Metal places importance on informed judgement. The team combines ongoing market research with first hand observation and professional dialogue to develop a fuller understanding of physical markets, supply chains and trading needs.
Strengthening professional knowledge
Participation in events such as Japan Bullion Market Networking forms part of the team’s continuing engagement with the international precious metals community. UniPrecious Metal will continue to follow market developments and exchange views with industry participants, supporting a disciplined and globally informed approach to its work. The photographs below capture the event and its discussion sessions.
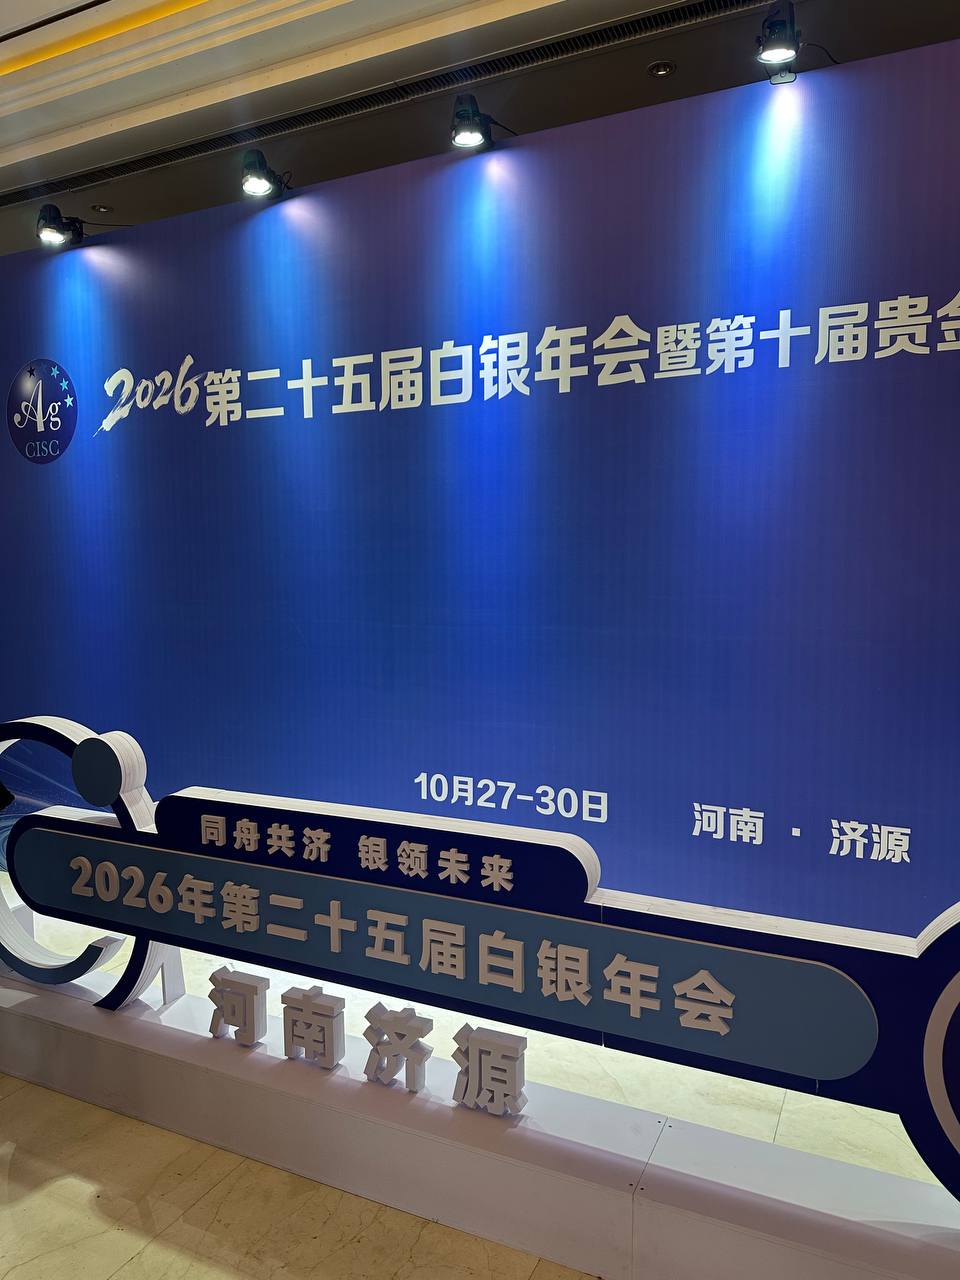
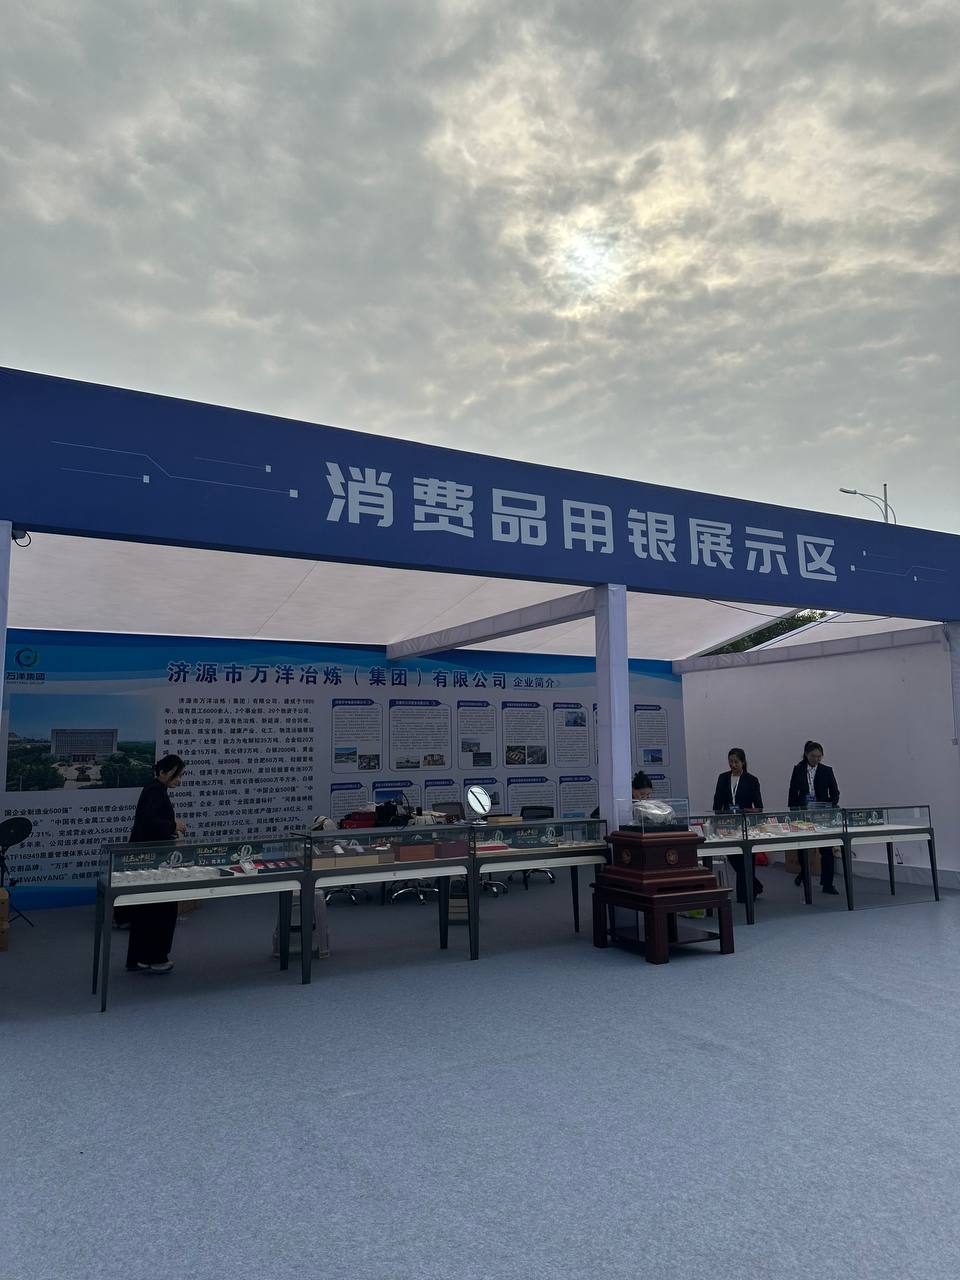
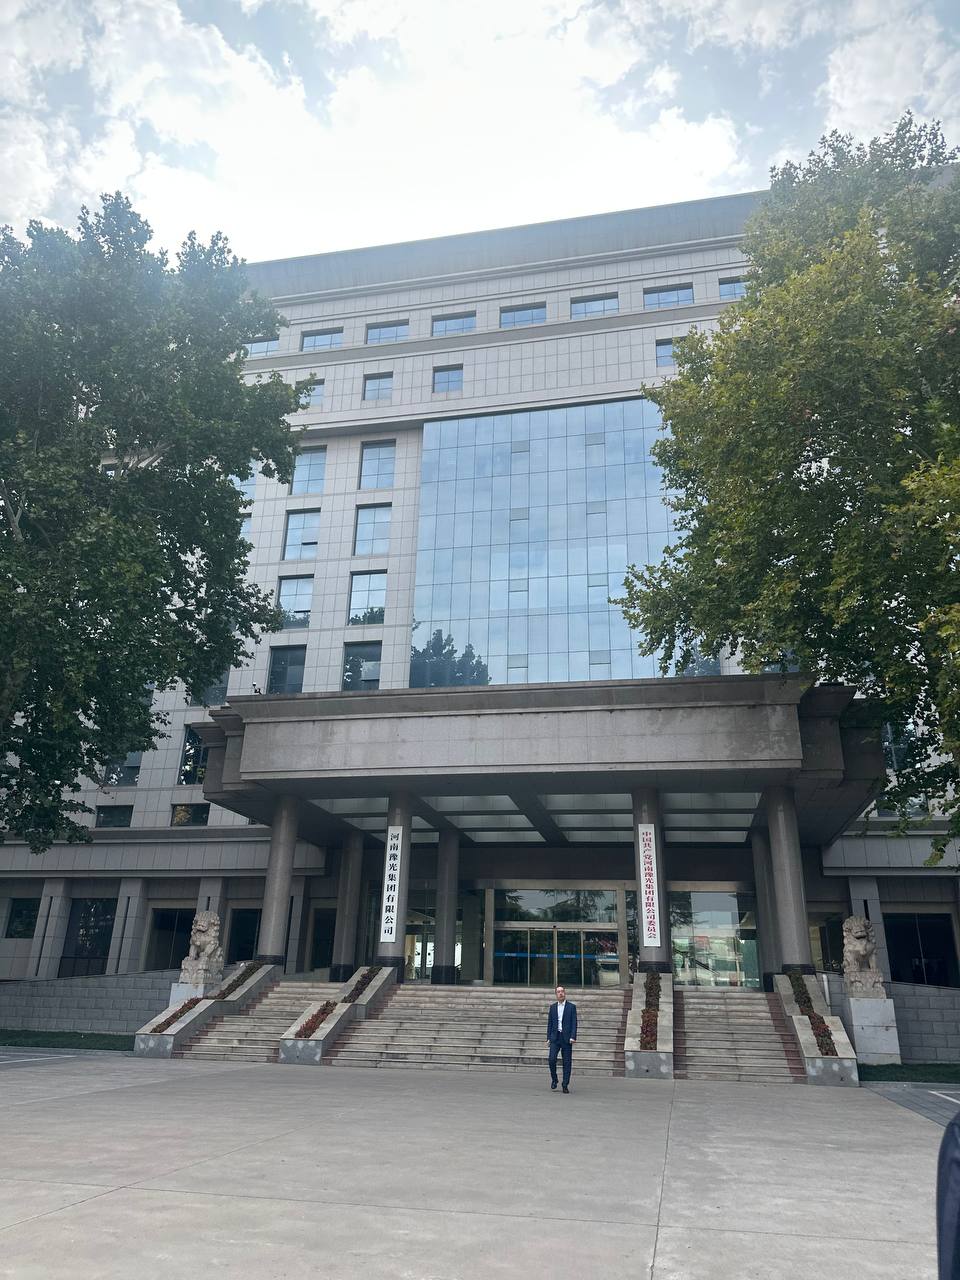
Jiyuan, Henan, 30 October 2026 — UniPrecious Metal attended the 25th Silver Conference in Jiyuan, held from 27 to 30 October, and visited Henan Yuguang Group during the trip. The programme gave the team an opportunity to examine developments across the silver industry, from market conditions and refining to industrial applications and consumer products.
Connecting market analysis with the silver value chain
Silver occupies a distinctive position as both a precious metal and an industrial material. Understanding its market therefore calls for attention to the wider value chain, including how supply, processing and end use evolve. At the conference, the UniPrecious Metal team visited the consumer silver exhibition area and followed discussions on industry developments. The subsequent visit to Yuguang Group added an on-site perspective to those conversations.
For UniPrecious Metal, direct industry observation complements ongoing market research. Bringing together insights from a professional conference and an industry visit helps the team assess developments in silver with greater context and discipline. It also reflects the company’s commitment to building practical knowledge of the markets it follows.
Continuing engagement with the industry
UniPrecious Metal will continue to follow changes across the silver value chain and engage with industry participants. The photographs below document the conference and the Yuguang Group visit.
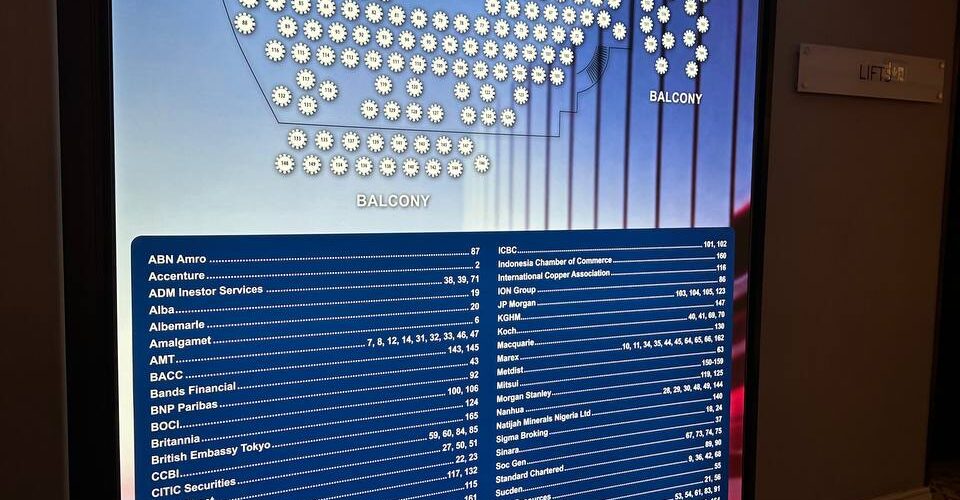
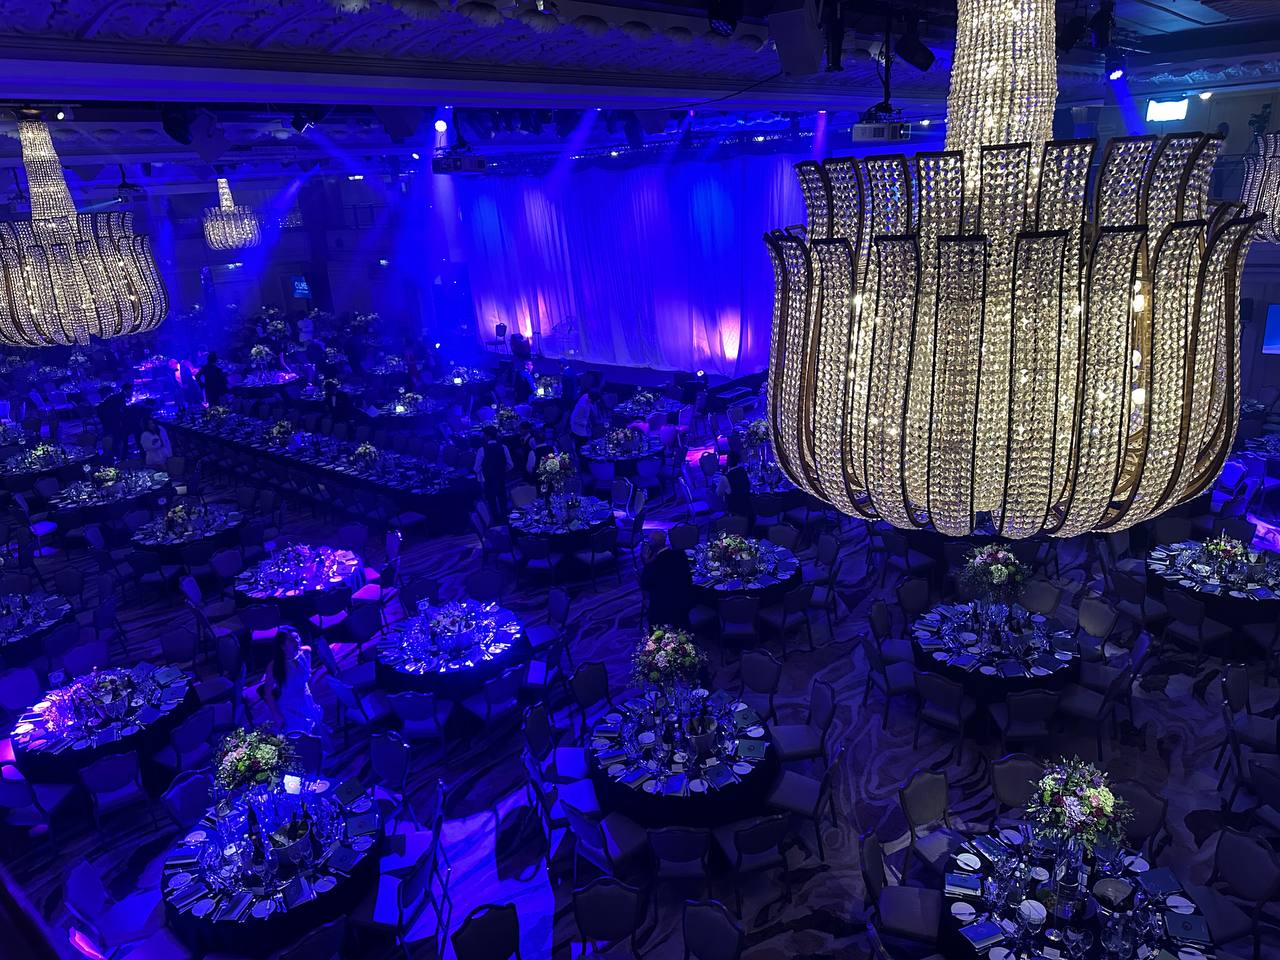
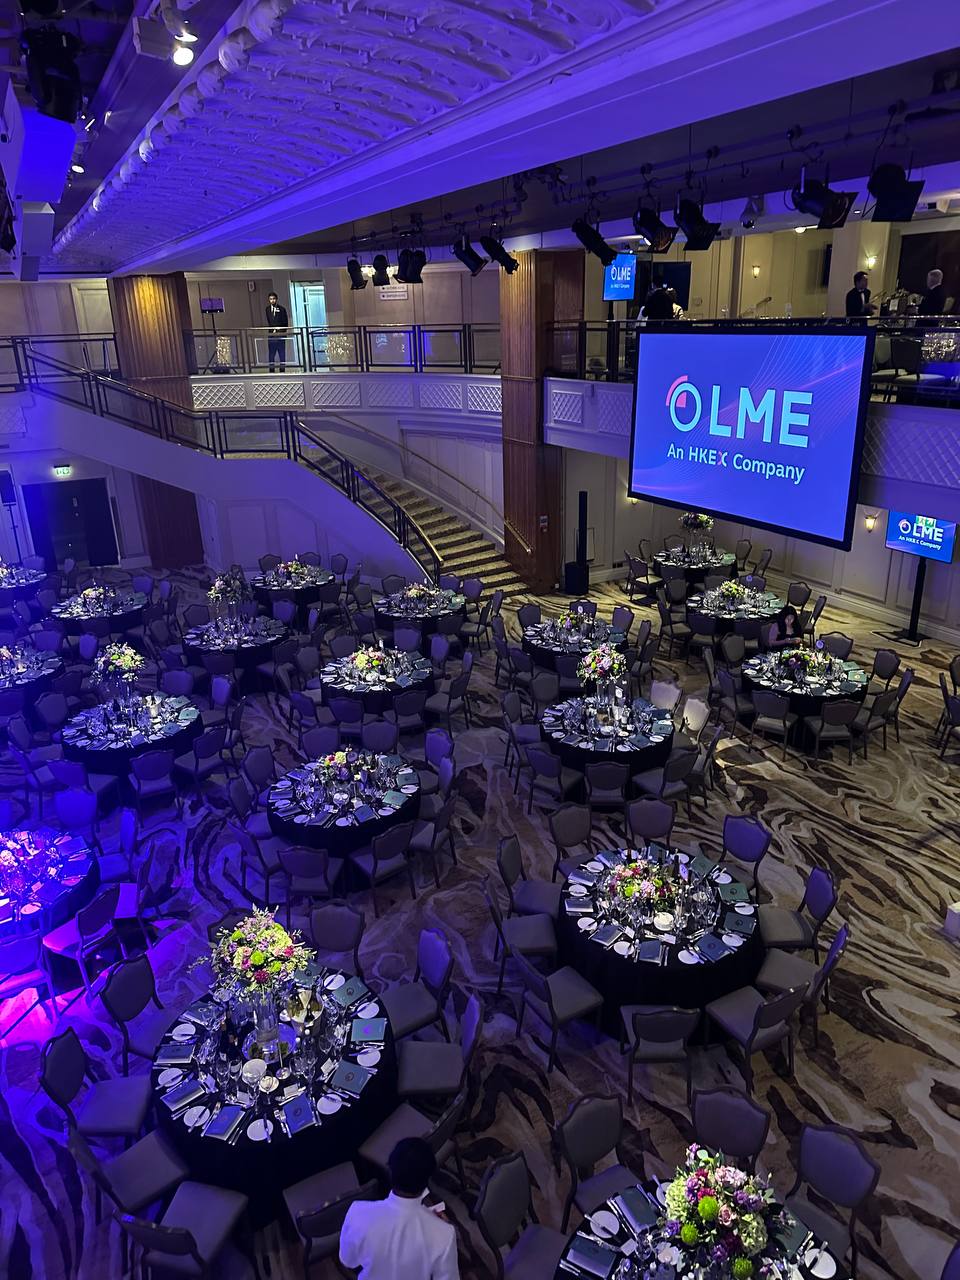
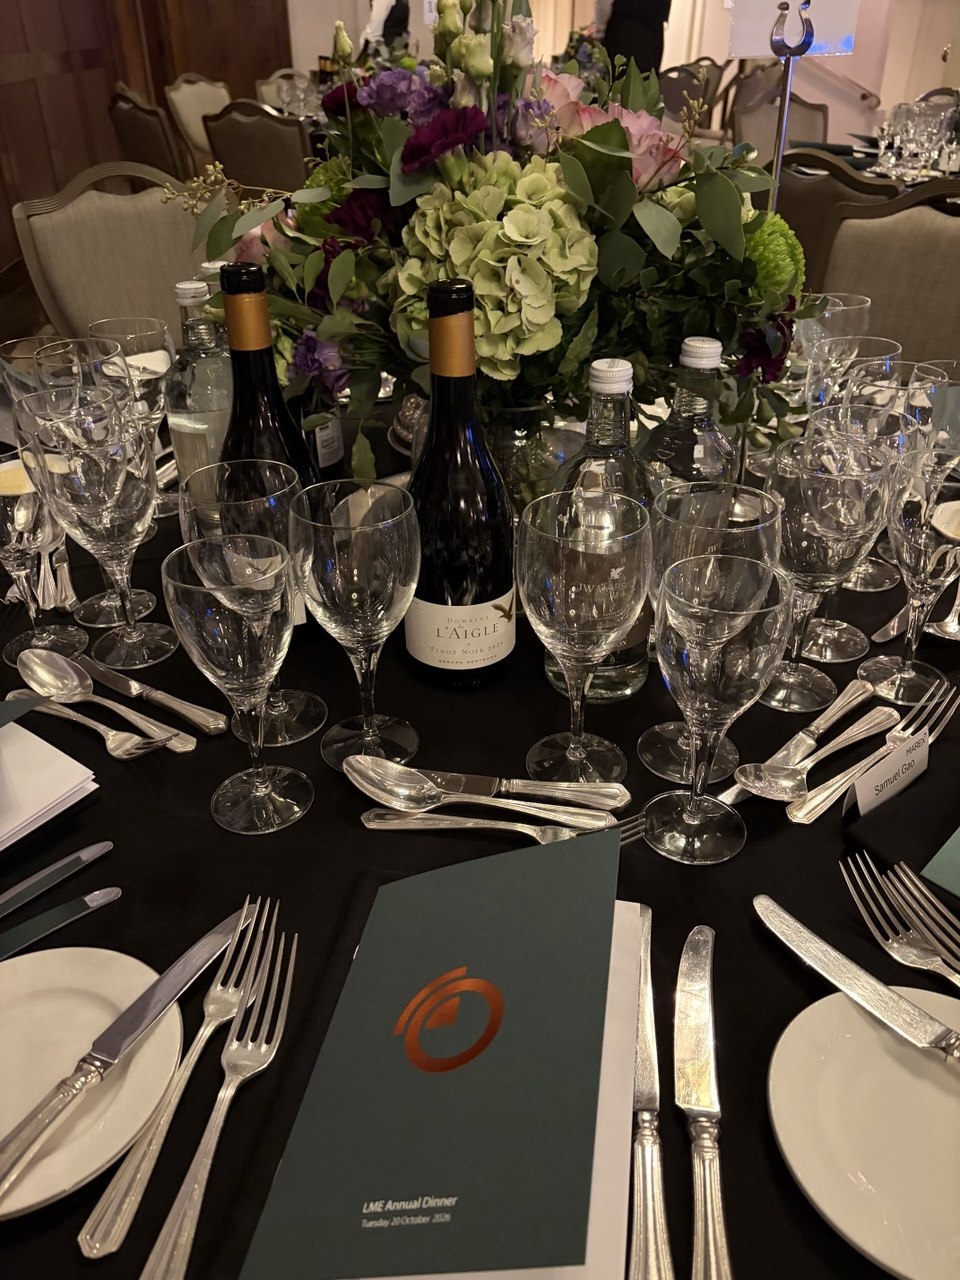
London, 20 October 2026 — The UniPrecious Metal team attended the London Metal Exchange (LME) Dinner 2026 at Grosvenor House Hotel. Held during LME Week, the annual dinner brings together participants from across the international metals industry and provides a setting for professional exchange.
Building perspective through industry engagement
For UniPrecious Metal, a Hong Kong based precious metals trading company, engagement with international industry events forms part of its ongoing effort to understand market structures, physical supply chains and cross border demand. The team combines observations from industry gatherings with its day to day market research to develop a broader, more grounded view of the factors shaping metals markets.
Following global market developments
UniPrecious Metal will continue to follow international market developments and engage with industry participants. The photographs below capture the venue and atmosphere of this year’s dinner.
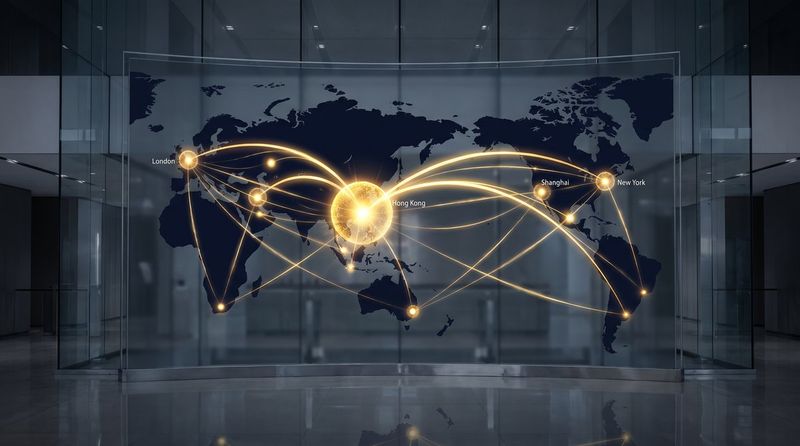
In an era in which globalization faces headwinds and the geopolitical map becomes increasingly fragmented, pricing and liquidity in precious metals markets are exhibiting pronounced regional characteristics. Against this backdrop, the liquidity of any single market can no longer satisfy the allocation needs of top‑tier institutional investors. UniPrecious, leveraging its superior cross‑market allocation capabilities, is becoming a critical bridge connecting global liquidity “islands.”
Challenges and Opportunities under Liquidity Fragmentation
Historically, London and New York have dominated global gold pricing. In recent years, however, strong physical demand in Asia—particularly China and India—and a reorientation of gold trade flows by countries such as Russia have produced material liquidity fragmentation across the global gold market.
Differences in supply‑and‑demand dynamics, regulatory regimes, and delivery standards among markets frequently produce meaningful price dislocations. For example, prices on the Shanghai Gold Exchange often trade at a premium to London spot, while prices in Dubai or Istanbul follow their own idiosyncratic volatility patterns.
For investors lacking a cross‑market network, such fragmentation translates into elevated liquidity risk and higher transaction costs; conversely, for dealers and trading firms with global reach and execution capabilities, it creates significant arbitrage opportunities and scope for strategic positioning.
Building a Seamless Global Trading Network
UniPrecious’s core competitive advantage lies in having constructed a seamless trading network that spans the world’s major financial centers.
We maintain deep local roots in Hong Kong and have established close partnerships with top liquidity providers in key markets including London, Zurich, New York, and Singapore. This extensive network coverage ensures that UniPrecious can secure the most competitive quotes and deepest liquidity for clients across time zones and varying market conditions.
When liquidity in a regional market dries up or when prices exhibit anomalous volatility, UniPrecious can rapidly route client orders to other markets with ample liquidity, thereby effectively mitigating the systemic risk associated with dependence on a single market.
Flexible Conversion between Physical and Book‑Entry Gold
Another important manifestation of cross‑market capability is the efficient conversion between physical gold and paper gold (book‑entry gold).
Many institutional investors face complex challenges in balancing physical delivery requirements with book‑entry holdings when implementing global asset allocations. UniPrecious’s solutions enable clients to flexibly change the form of their gold holdings across different jurisdictions.
For example, a client may acquire book‑entry gold in London and then, via UniPrecious’s network, convert it into physical gold bars deliverable in Hong Kong or Singapore. Our specialised logistics and compliance teams ensure that the entire conversion process is legally compliant, secure, and efficient, while minimizing frictional costs.
Enabling Institutional Clients’ Global Strategies
In a world of pervasive uncertainty, asset safety and liquidity are the foremost considerations for institutional investors.
UniPrecious’s cross‑market allocation capabilities not only provide clients with broader market visibility and a richer set of arbitrage instruments, but also deliver the robust infrastructure necessary for global asset deployment.
Whether supporting a family office seeking hedges against geopolitical risk or an asset manager pursuing stable returns, UniPrecious—through its distinguished global execution capabilities—acts as an indispensable strategic partner in the global precious metals market. We are committed to dismantling market barriers, enabling liquidity to flow freely, and creating tangible cross‑border value for our clients.
In a macro environment of low interest rates and scarce yield-bearing assets, a proliferation of investment platforms marketing themselves as “gold wealth management” or “principal-protected, high-yield” offerings has emerged. Behind the glossy marketing rhetoric, however, often lurk fatal systemic risks. For professional investors, penetrating the underlying mechanics of these products is essential to avoid falling into blow-up traps.
The Fundamental Paradox of “Principal Protection with High Yield”
The first iron law of financial markets is that return and risk are positively correlated. Physical gold does not produce any interest (yield). So where do those “gold wealth management” products that promise fixed annual returns of 8% or even 10%+ actually obtain their profits?
A close analysis of their business models typically reveals two possibilities:
First, the platform may be diverting clients’ gold or funds into high-risk speculative trades (e.g., high-leverage futures, options speculation), attempting to generate high returns to pay client interest. Once markets experience violent volatility, the platform’s positions are highly susceptible to margin calls and forced liquidation, ultimately resulting in total loss of clients’ principal.
Second, and more maliciously, the platform may engage in no substantive investment at all and instead operate a classic Ponzi scheme, using new clients’ funds to pay interest to existing clients. The collapse of such a model is only a matter of time.
Shadow Banking and Pooled-Fund Risk
Many precious-metals platforms that blow up are, in substance, unregulated “shadow banks.”
Regulated financial institutions must strictly observe segregation of client funds from their own capital. Problematic platforms, however, often establish opaque “pooled funds” in which client monies are commingled with operating capital.
In the absence of independent third-party custody, the platform’s ultimate controllers can readily misappropriate funds. When the platform faces a liquidity run or regulatory investigation, the pool can be exhausted in an instant; investors then awaken to the reality—too late.
The “Boiling Frog” of High-Leverage Trading
Beyond principal-protected products, another category of high-risk trap is high-leverage over-the-counter (OTC) trading platforms.
These platforms typically offer leverage of 100x or even 500x to attract retail clients seeking outsized returns from small capital. The hidden profit model, however, is that the platform itself often acts as the counterparty to clients’ trades (the B-Book model).
When clients lose, the platform profits. To secure their own gains, some unscrupulous platforms will exploit back-office privileges to manufacture slippage, widen spreads, or even deliberately sever clients’ trading access during periods of extreme volatility, preventing clients from closing positions and forcing liquidations. This mechanism—acting as both the referee and the participant—dooms investors to an absolute disadvantage.
Core Dimensions of Professional Due Diligence
To avoid these blow-up traps, investors must establish a rigorous due diligence framework.
First, scrutinize licenses and regulation. Genuine regulatory authorizations (for example, a Hong Kong SFC license or a UK FCA authorization) carry substantial credibility and impose stringent compliance requirements. Many problematic platforms, by contrast, present lenient licenses from certain offshore jurisdictions as a fig leaf to confuse investors.
Second, verify custody arrangements. Confirm that client funds are held in segregated third-party bank accounts or by independent custodians and are not exposed to the platform’s liabilities.
Finally, apply common sense. Maintain a high degree of skepticism toward any product that promises “risk-free, high returns.” In precious-metals investing, true value derives from asset safety and liquidity, not illusory high yields. Choosing regulated, transparent, and well-established professional dealers is the proper path to preserving wealth.
As the global economic center of gravity shifts toward Asia, the strategic importance of Asia’s gold markets has increased markedly. In this process, Hong Kong and Singapore—two premier financial centers—are engaged in intense competition to establish themselves as the preferred regional hubs for precious metals storage and trading. For institutional investors, a thorough understanding of the differences in storage infrastructure between the two jurisdictions is critical to optimizing asset-allocation strategies.
Differences in Geography and Market Hinterland
The competition between Hong Kong and Singapore is first manifested in their geographical location and the market hinterlands they serve.
Hong Kong’s primary advantage lies in its proximity to mainland China—the world’s largest gold consumer and producer. With the advancement of physical-connectivity mechanisms (e.g., arrangements enabling cross-border physical flows), Hong Kong’s role as the gateway connecting the mainland gold market to international markets is irreplaceable. Storing gold in Hong Kong not only facilitates participation in international market trading but also allows investors to flexibly capture arbitrage opportunities with the mainland market as they arise.
Singapore sits at the strategic heart of Southeast Asia; its market hinterland primarily covers ASEAN countries and emerging economies such as India. The Singaporean government has actively promoted the city-state as a regional precious-metals distribution center. For investors whose principal business is based in Southeast Asia, Singapore offers clear logistical advantages.
Comparison of Tax Policy and Regulatory Environment
On tax policy, both jurisdictions exhibit strong competitive features.
Hong Kong is renowned for its simple, low-tax regime: gold imports/exports and trading are exempt from customs duties and value‑added tax (VAT), thereby providing investors with very low transaction friction costs.
Singapore has matched this competitiveness. Since 2012 it has exempted investment-grade precious metals (IPM) from Goods and Services Tax (GST). This policy has materially stimulated the development of Singapore’s physical gold market.
Regarding compliance and regulation, both jurisdictions maintain legal frameworks that are closely aligned with international standards. Hong Kong, however, retains certain advantages in the depth and breadth of its financial infrastructure. In particular, the recent introduction of a central clearing system has further enhanced transactional safety and transparency.
The Vaulting and Security Standards Showdown
For physical gold, the security and professional standards of vaulting facilities are of paramount importance.
Hong Kong is actively expanding vault capacity and plans to construct a super-vault near the airport with capacity on the order of one thousand tonnes. This initiative is designed to alleviate the current bottleneck in LBMA‑certified vault capacity. Security firms such as Brinks and Malca‑Amit have extensive operational experience in Hong Kong and can provide top‑tier security services.
Singapore is globally renowned for its modern Freeport facilities. The Singapore Freeport features best‑in‑class security systems and environmental controls for temperature and humidity, attracting numerous leading international galleries, auction houses, and precious‑metals dealers. Singapore’s vaulting facilities possess distinctive appeal in terms of privacy and high‑end bespoke services.
Optimal Institutional Configuration: Multi‑Jurisdictional Distribution and Flexible Logistics
For large institutional investors and family offices, choosing only one location between Hong Kong and Singapore may not be the optimal strategy.
A truly professional asset‑allocation approach should, from the perspective of geopolitical risk diversification, implement a multi‑jurisdictional vaulting strategy. Dispersing core holdings across top‑tier vaults in Hong Kong, Singapore, and other jurisdictions such as Zurich maximizes resilience against systemic risk concentrated in a single region.
In that process, selecting dealers with global networks and cross‑market transfer capabilities is critical. High‑quality dealers can not only provide clients with competitive vaulting quotes across jurisdictions but also ensure the secure, efficient movement of assets between legal regimes. In a landscape where two Asian hubs coexist, flexible logistics and redeployment capability will determine success.
Over the past several years, the most significant structural change in the global gold market has been the sustained, large-scale purchases of gold by central banks. This phenomenon is not merely a short-term market fluctuation; it is a concrete manifestation of a deep restructuring of the global monetary system. For professional investors, understanding the underlying logic of central bank gold purchases is key to grasping future trends in gold pricing.
The Strategic Inevitability of De‑dollarization and Reserve Diversification
Since the dismantling of the Bretton Woods system, the US dollar has dominated global foreign-exchange reserves. In recent years, however, the dramatic expansion of US public debt and the intensification of geopolitical competition have placed unprecedented pressure on the perceived “risk‑free” status of dollar assets.
In particular, the financial sanctions imposed on Russia following the 2022 Russia–Ukraine conflict fundamentally altered central banks’ assessment of reserve safety. Concentrating national wealth in a single sovereign currency exposes countries to the latent risk of that currency being “weaponized”—a strategic vulnerability that central banks can no longer ignore.
Against this backdrop, gold—being the sole ultimate reserve asset that does not depend on any sovereign credit—has seen its strategic value accentuated. Increasing gold reserves has become an inevitable choice for emerging-market countries seeking reserve diversification and enhanced financial resilience.
Structural Shift in Gold-Purchasing Entities
A granular analysis of central-bank gold-purchase data reveals a fundamental transformation in the composition of buyers.
In the late 20th and early 21st centuries, central banks in Western developed economies were net sellers of gold. Since approximately 2010, however, emerging-market economies (for example, China, Russia, India, and Turkey) have progressively become the predominant buyers.
This structural change reflects the eastward shift of global economic power. Having accumulated substantial trade surpluses, these countries have an urgent need to convert those surpluses into safer, sovereign‑independent physical assets. Purchases driven by state strategic considerations are relatively price‑insensitive, thereby providing a materially firmer floor under gold prices.
Challenge to Traditional Pricing Models
Conventional gold‑pricing models typically place heavy weight on US real interest rates (Real Interest Rates) and the US dollar index. Over past decades, gold has exhibited a pronounced negative correlation with US real rates.
Since 2022, however, this classical pricing relationship has demonstrably broken down. Despite aggressive Federal Reserve tightening and a marked rise in real yields, gold did not collapse as traditional models would predict; on the contrary, it repeatedly reached new highs.
The principal reason for the failure of this pricing model is the strength of central‑bank demand. Central banks’ gold purchases are not motivated by short‑term rate arbitrage but by long‑term considerations of national security and strategic reserve policy. This form of “non‑economic” buying power is actively reshaping the paradigm by which gold is priced.
Strategic Implications for Institutional Allocation
The central‑bank gold‑buying wave carries important strategic implications for institutional investors.
First, the effective price floor for gold has meaningfully shifted higher. With continuous central‑bank bid support, the probability of deep, sustained drawdowns in gold prices has materially decreased.
Second, investors assessing gold should reduce singular reliance on US interest‑rate policy and instead give greater weight to geopolitical developments and the broader process of global monetary‑system restructuring.
Finally, following the trajectory of “smart money” (Smart Money), allocating gold as a core asset to hedge tail risk (Tail Risk) and fiat‑currency depreciation has become an essential element of constructing resilient portfolios. In an increasingly uncertain world, the strategic value of gold is being rediscovered and more deeply appreciated.
The Hong Kong gold market is evolving, and the role of dealers is evolving with it.
The Value of Execution Capability
In this period, a dealer’s core competitive advantage lies not in licensing or capital, but in execution capability.
Specifically, this means the ability to move assets swiftly, efficiently, and cost-effectively between different markets. Arbitrage opportunities between Hong Kong, Shanghai, and London represent revenue sources for agile dealers. This requires deep market understanding and a well-established trading network.
UniPrecious maintains deep local roots in Hong Kong, with close relationships to major clearing institutions and warehousing providers. This affords us a decisive execution advantage.
The Importance of Transparent Pricing
In traditional OTC trading, pricing lacks transparency. Dealers can adjust quotations based on client circumstances — effectively a hidden form of value extraction.
We believe transparent pricing mechanisms benefit both parties. Clients understand their costs; dealers build trust. Over the long term, this model proves more sustainable.
Under Hong Kong’s new clearing system, transparent pricing becomes more feasible. We are building pricing mechanisms based on real-time market liquidity rather than dealer subjectivity.
Depth of Risk Management
In gold trading, risk management is frequently neglected. Most dealers focus solely on transaction volume, not risk.
Our approach differs. For every transaction, we conduct thorough risk assessment. This encompasses counterparty risk, market risk, and liquidity risk.
This cautious approach may cause us to lag on certain short-term opportunities. Over the long term, however, it represents a necessary condition for protecting client assets and maintaining business sustainability.
Cross-Market Allocation Support
With the launch of “physical linkage,” cross-market allocation becomes a new opportunity. Yet it also introduces new complexity.
What we provide clients extends beyond transaction execution to comprehensive cross-market allocation solutions. This includes in-depth analysis of each market’s regulatory, tax, and exchange rate factors, along with thorough risk assessment.
Such holistic support requires professional teams and deep market experience.
Long-Term Client Relationships
We do not pursue one-off large transactions. We pursue long-term collaborative relationships with clients.
This means we must genuinely understand client needs rather than simply promoting products. We must alert clients to potential risks when markets shift. We must provide substantive assistance when clients face difficulties.
Building such relationships requires time. Once established, however, they become valuable assets for both parties.
Outlook
The future of the gold market will be more complex. New market mechanisms, new participants, and new risks will continue to emerge.
In this environment, a dealer’s value lies in helping clients navigate this complexity. Not simply providing transaction execution, but delivering complete solutions.
UniPrecious is developing in this direction. We believe this represents the future trajectory of the gold trading market.
The gold market appears straightforward, yet risks abound. Most institutional investors have encountered pitfalls here.
The Illusion of Liquidity
“Excellent liquidity” is among the most frequently heard claims in gold trading. But what constitutes genuine liquidity?
Liquidity is not merely whether one can sell, but whether one can sell at a reasonable price within a reasonable timeframe. Under normal market conditions, gold liquidity is indeed respectable. But under market stress?
During the 2020 pandemic, global financial markets experienced a liquidity crisis. At that time, even LBMA-standard gold saw trading spreads widen dramatically. Certain non-standard gold products found no buyers whatsoever.
This teaches us that liquidity is conditional. When market conditions deteriorate, liquidity can evaporate rapidly.
Counterparty Risk
Most investors hold gold certificates or warehouse receipts rather than physical metal. This means they effectively bear the credit risk of the dealer or custodian.
History records instances of dealers collapsing and investors being unable to retrieve their gold. Such cases remind us that counterparty creditworthiness requires continuous monitoring.
Even major banks can encounter difficulties under market stress. During the 2008 financial crisis, certain prominent banks experienced significant credit rating downgrades. Had investors held gold certificates from these institutions, they would have faced substantial risk.
The Non-Standard Gold Trap
The market offers numerous non-standard gold products. These typically advertise “high purity” and “low cost” advantages. The reality is more complex.
First, poor liquidity. Non-standard gold commands low recognition in global markets, facing significant discounts upon monetization.
Second, authentication difficulties. Certain non-standard gold products have unclear provenance, making verification challenging. The risks this creates are frequently underestimated.
Third, regulatory risk. Certain non-standard gold may involve smuggling or money laundering concerns. Holding such gold may expose investors to legal liability.
The Dangers of Leveraged Trading
Certain gold trading platforms offer leveraged trading. While this appears to amplify returns, it equally amplifies risk.
Leveraged trading is particularly dangerous during market volatility. When gold prices declined sharply in 2011, certain leveraged investors suffered devastating losses. Some faced margin calls, losing more than their initial investment.
Leveraged trading suits short-term traders, but for long-term holders, the risk is typically unwarranted.
Assessing Counterparty Risk
When selecting a dealer, thorough investigation of their background and financial condition is essential.
Key indicators include: capital adequacy ratio, liquidity ratio, and standing within global clearing systems. Yet these metrics have inherent limitations. Genuine risk assessment requires deep understanding of a dealer’s business model, client structure, and market position.
Moreover, such assessments require regular updating. Market conditions change rapidly, and dealers’ risk profiles evolve accordingly.
Physical Gold Verification
For those choosing to hold physical gold, regular independent audits and physical inspections are necessary.
Yet this too carries costs. Each audit requires payment and may involve moving the gold, introducing additional risk. Physical holding is therefore not entirely risk-free.
Stress Testing
Institutional investors should regularly stress-test their gold investment portfolios. Simulating various extreme scenarios enables assessment of portfolio resilience.
This includes scenarios such as: gold price crashes, liquidity drought, and counterparty default. Through such testing, one gains clearer understanding of risk exposure.
Conclusion
Gold investment appears simple, yet risk management is highly complex. Most investors suffer losses by neglecting these hidden risks. The key lies in maintaining clear risk awareness and a systematic risk management framework.
Hong Kong Gold Market: Opportunities and Realities
The upgrade of Hong Kong’s gold market has attracted considerable media attention, yet the reality is more nuanced than headlines suggest.
The Significance of Central Clearing
The central clearing system that commenced trial operations in July represents a genuinely important development. To understand its true value, however, one must first appreciate the problem it solves.
Historically, Hong Kong gold trading was predominantly over-the-counter (OTC). Banks and dealers transacted directly with one another, without a unified clearing center. This created several challenges: counterparty risk proved difficult to control, price transparency was insufficient, and large transaction costs remained elevated.
The central clearing system transforms this landscape. Through a unified clearing mechanism, counterparty credit risk is distributed across the clearing house, reducing individual dealers’ risk exposure. For substantial holders, this means a safer trading environment.
Yet this does not mean Hong Kong has become London. The London gold market has evolved over centuries, with numerous participants and deep liquidity. Hong Kong’s system has only just launched, and participants remain in observation mode. Genuine liquidity depth requires time to develop.
First, regulatory considerations. Hong Kong and Shanghai operate under different regulatory frameworks, with divergent tax treatments. Transferring gold from Hong Kong to Shanghai involves not merely logistics, but compliance, customs clearance, taxation, and multiple other stages. These costs are insufficiently considered by most investors.
Second, liquidity concerns. The Shanghai Gold Exchange’s participants are primarily domestic institutions and individual investors, with limited connectivity to international markets. This means that gold flowing from Hong Kong to Shanghai may experience reduced monetization capability.
Third, risk factors. Cross-market holdings involve exchange rate risk, policy risk, and other variables. Arbitrage opportunities may appear substantial, yet actual returns may be offset by various risk factors.
The Appeal of Tax Incentives
The Hong Kong government’s tax incentive policies are genuinely attractive. However, fully utilizing these benefits requires meeting specific conditions. The details of these conditions remain unclear to most investors.
Furthermore, tax policies are subject to change. Investment strategies dependent on tax incentives carry elevated long-term risk.
Warehousing Cost Concerns
Hong Kong’s ambition to expand warehousing capacity to 2,000 metric tonnes within three years requires substantial investment. This investment will ultimately translate into warehousing costs. In the short term, costs may be suppressed to attract clients. Over the longer term, however, cost increases are inevitable.
For substantial holders, rising warehousing costs will directly impact holding returns. This factor warrants serious evaluation.
Institutional Investor Choices
In this period of change, institutional investors must exercise greater caution. Not all new mechanisms warrant immediate participation. Some opportunities genuinely exist, yet some risks are obscured by market enthusiasm.
The key lies in maintaining clear risk assessments and continuous monitoring of market developments.
Our product range is designed to meet the unique needs of every investor, ensuring you can find exceptional options that perfectly align with your requirements and goals.